On March 8, 2024, the Minnesota Attorney General announced a lawsuit naming GoodLeap LLC, Sunlight Financial LLC, Solar Mosaic LLC and Dividend Solar Finance LLC over alleged undisclosed solar-loan dealer fees. The announcement describes allegations, not findings about every loan. It is not a current docket-status check.
$170,000+ recovery
Against Sunlight Financial · Solar fraud arbitration
- $113,000 loan cancelled
- UCC lien removed
- Credit repaired
- $58,000 cash to client
Past results do not guarantee a similar outcome. Every case is different.
This article explains that public action and records a homeowner can gather. A company being discussed in the lawsuit does not mean Bennett Legal accepts matters involving that company. The firm's current financing scope is stated below.
What the Minnesota Lawsuit Says About Hidden Solar Loan Dealer Fees
Here's the basic problem the lawsuit describes.
When you signed up for solar, you were probably shown a low monthly payment and a low interest rate. That sounded great. But according to Minnesota's Attorney General, the companies didn't clearly tell you about something called a dealer fee — extra money added to your loan behind the scenes.
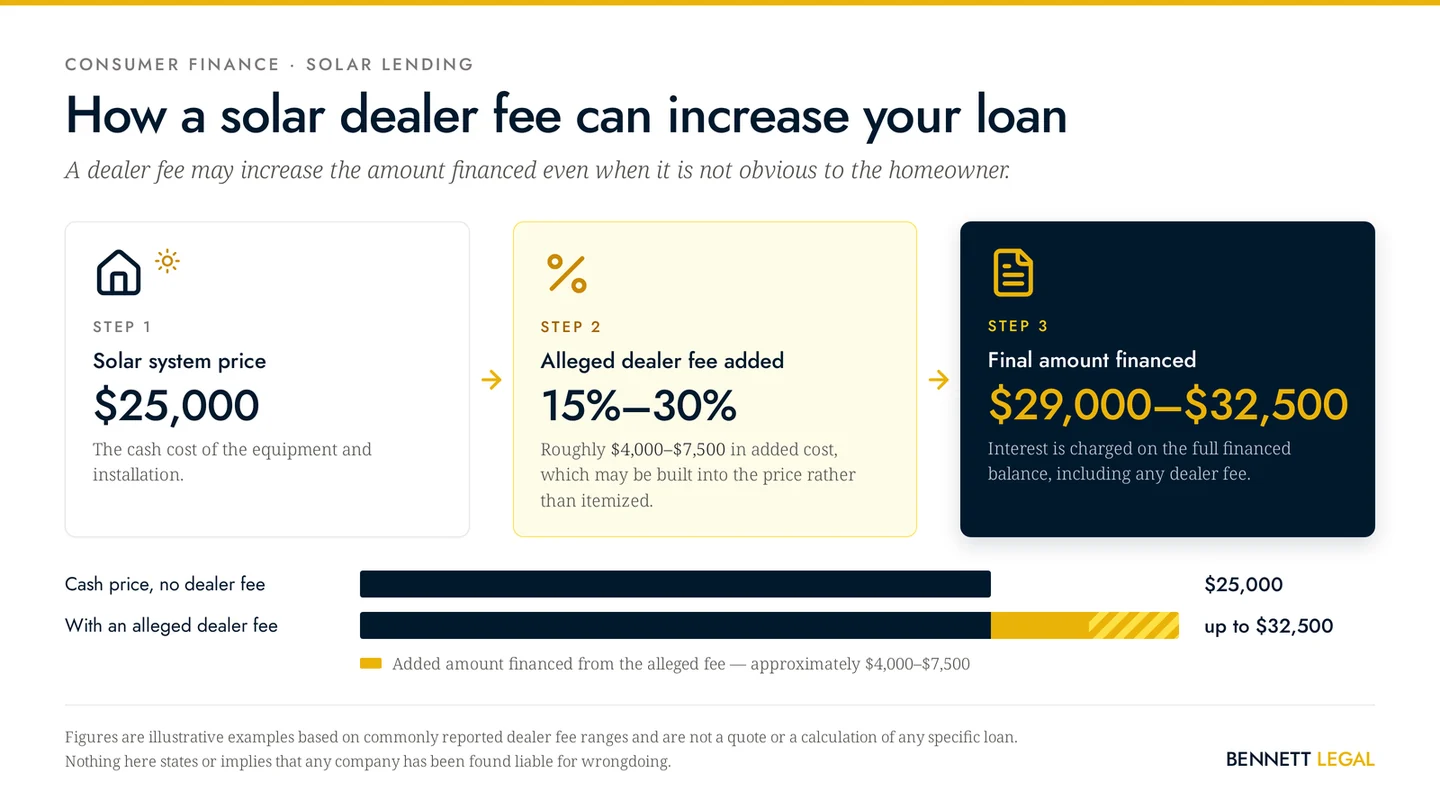
Think of it this way. You agreed to finance a $25,000 solar system. But without you knowing, a dealer fee of $4,000 to $7,500 was quietly added. Now you're borrowing $29,000 to $32,000 — for the same system. The monthly payment might look similar, but you're paying far more in total.
Here's what Minnesota says happened:
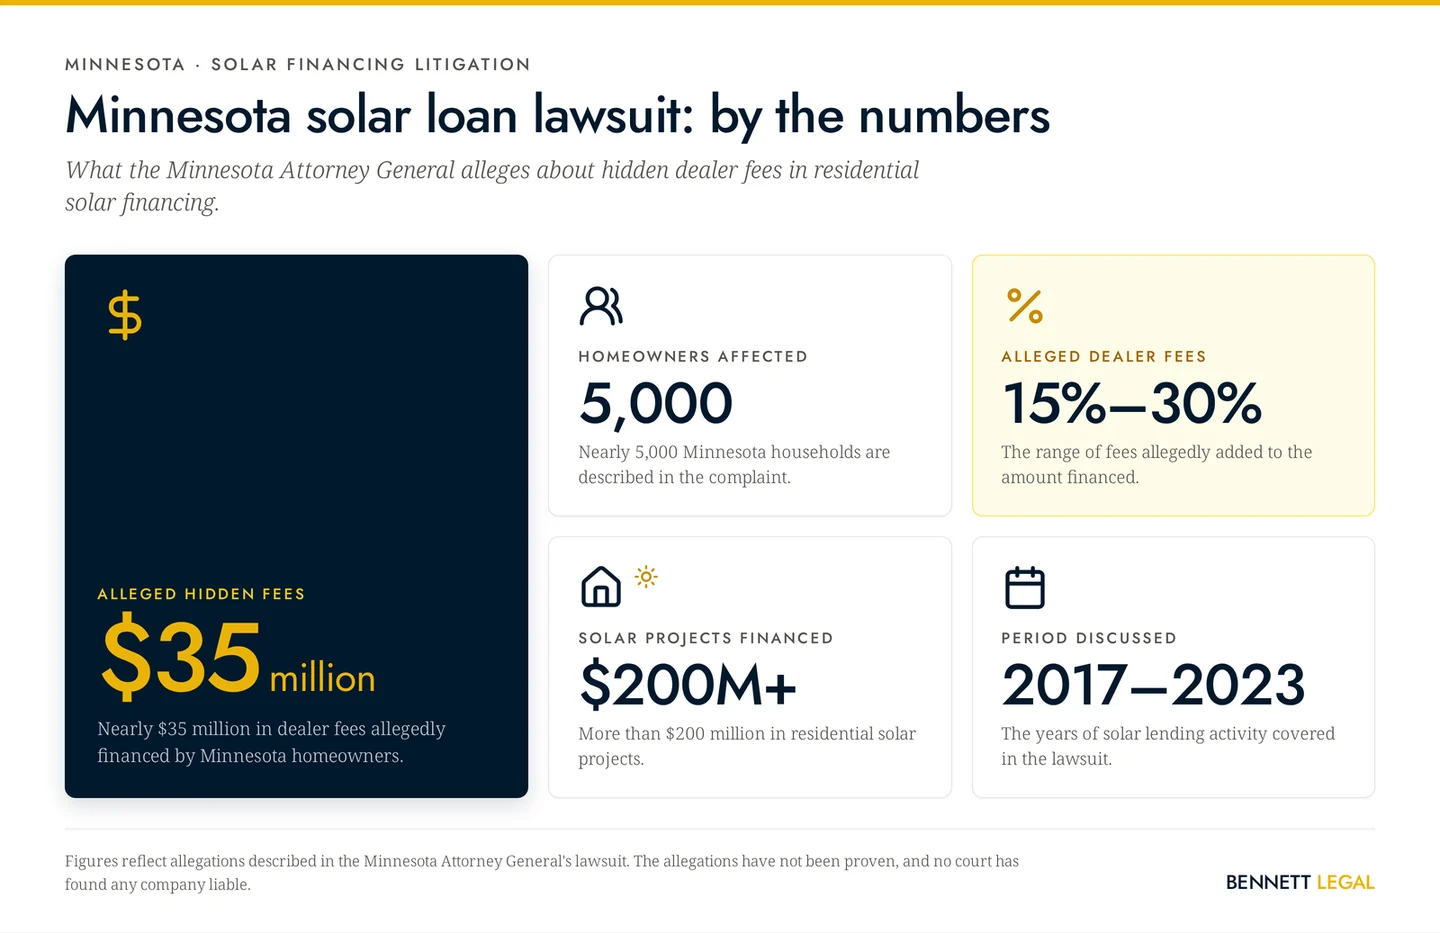
- Nearly $35 million in hidden fees were added to solar loans in Minnesota
- Almost 5,000 homeowners in Minnesota were affected
- These fees added 15% to 30% to the actual cost of the solar system
- More than $200 million in solar projects were involved
- This went on from 2017 to 2023
The companies kept your attention on your monthly payment, the interest rate, and how much money solar would supposedly save you. Meanwhile, the real loan amount — already padded with the hidden fee — didn't get much attention. Minnesota says that's not okay under state law.
Here's what that means for you: if you signed a solar loan between 2017 and 2023 through one of these four companies, the amount you're paying back may be thousands of dollars more than what your system was actually worth.
Who Are These Four Companies?
GoodLeap LLC
GoodLeap is one of the biggest solar loan companies in the country. You might know it by its old names — it used to be called Loanpal and, before that, Paramount Equity Mortgage.
Minnesota named GoodLeap as a main defendant in its lawsuit. GoodLeap also shows up in the Sunlight Financial lawsuit and in thousands of complaints from real customers — through the BBB, the CFPB, news investigations, and private lawsuits. You can learn more about your rights on our GoodLeap solar loans page.
Sunlight Financial LLC
Sunlight Financial is sued in the same case. Minnesota says it ran the same playbook: low advertised rates, hidden fees folded into the loan amount. If you have a Sunlight Financial loan, the hidden dealer fee structure is exactly what's at issue in this case — and what Bennett Legal has taken to arbitration on behalf of Texas homeowners.
Solar Mosaic LLC
Solar Mosaic is another national solar lender named in the case. A TIME magazine investigation found that Solar Mosaic had 185 complaints filed with the federal Consumer Financial Protection Bureau (CFPB) — more than GoodLeap's 162 in the same review.
Dividend Solar Finance LLC
Dividend Solar is owned by Fifth Third Bank. In the TIME investigation, Fifth Third had 3,717 CFPB complaints as a parent bank. Dividend Solar is named in the Minnesota lawsuit alongside the other three companies.
5 Problems Homeowners Keep Reporting
Minnesota's lawsuit focuses on hidden fees. But homeowners who financed solar — especially through GoodLeap — keep running into five different problems. Here's what they are and what they mean for you.
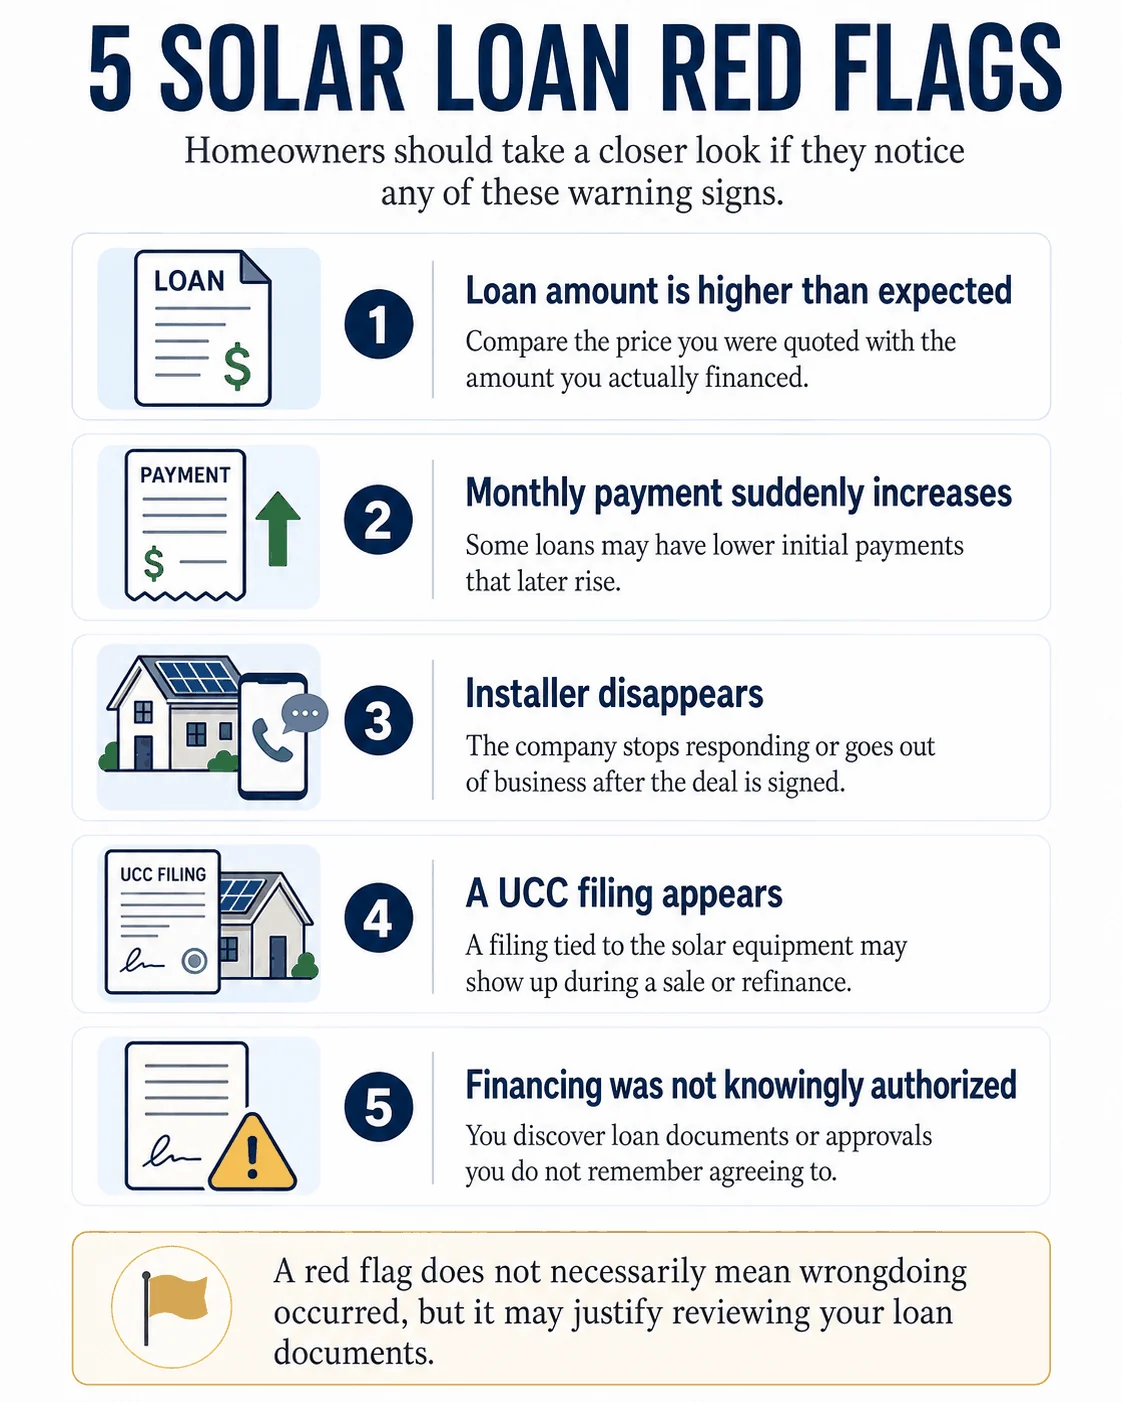
1. Hidden Fees That Made Your Loan Much Bigger
This is the big one — the whole reason Minnesota filed the lawsuit.
You thought you were borrowing enough to pay for your solar system. But a "dealer fee" — money the contractor gets paid back by the lender — got added to your loan. No one circled it in red. No one said, "Hey, your loan is $5,000 more than the system costs."
Minnesota says these fees bumped up the total cost by 15% to 30%. So if your solar system cost $25,000, you may have actually borrowed $29,000 to $32,500 — without clearly knowing it.
If your loan balance looks bigger than what you thought you were paying for your system, this might be why. Our guide on how to spot a predatory solar financing deal walks through exactly what your loan documents should — and shouldn't — say.
2. Your Payment Jumped After Year One
A lot of solar loans have low payments at first. That's because they're built around a tax break — the federal solar tax credit (ITC) — that the company assumed you would get and apply to your loan within the first 12 to 18 months.
But not everyone gets the full credit. Some people don't qualify at all. And many homeowners were never clearly told: if you don't apply that tax credit to your loan, your monthly payment goes up.
If your solar payment suddenly got bigger after the first year, this is most likely why. Our post on solar tax credit timing mistakes explains how this catches homeowners off guard — and what you can do if the lender never told you.
3. Your Solar Company Disappeared — But the Loan Didn't
This is one of the most frustrating situations we see. The company that installed your solar panels went out of business. Or they stopped answering your calls. Or the system was never finished. Or it never worked right.
But the loan is still there.
That's because in many cases, the installer quickly handed your loan over to the lender. Once that happens, the lender says your agreement to pay is separate from any problems with the installer. So even if your system doesn't work, you may still owe the full loan amount to GoodLeap or another lender.
4. A UCC-1 Was Filed
A UCC-1 financing statement may identify solar equipment as collateral. A county fixture filing may appear in real property records, while a state UCC filing may appear in a separate system. The filing and agreement determine what is described; a name match alone does not establish a filing's effect or whether it concerns your property.
Check both county and state records and save the actual document, attachments and any later amendments or terminations. Our solar UCC-1 lookup guide provides dated official starting points and explains what to keep for review. If a sale or refinance is planned, have the agreement and recorded documents reviewed rather than assuming a result from an index entry.
5. Loans Taken Out in Someone's Name Without Their Permission
A major TIME magazine investigation found cases where solar loans were taken out using fake names or without the homeowner's knowledge. If a loan was opened without your authorization, gather the agreement, signature history, account notices and any related recorded financing documents for review.
GoodLeap said fraud made up less than 0.05% of its loans and that it worked with federal investigators. The FBI reportedly looked into some of the cases TIME covered.
If you think a solar loan was opened in your name without your permission, that's serious. It can involve identity theft and other federal crimes on top of whatever civil options you have. Read our breakdown of solar panel identity theft scams to understand how this typically happens and what evidence you'll need.
Free consultation
Solar panel contract problems?
We review GoodLeap, Sunlight Financial, EverBright loan/RIC and BrightOak financing matters. Free case evaluation.
This Isn't Just a Minnesota Problem
The Attorney General's announcement concerns alleged practices affecting Minnesota transactions. It does not determine a homeowner's rights in another state or establish what happened in a particular sale. Compare your own agreement, proposal, payment records and sales communications; applicable law and possible options depend on the state and facts.
Watch for these warning signs:
- Your loan balance is higher than what you agreed to pay for the solar system
- Your monthly payment went up after the first year
- Your solar panels don't work as well as promised
- You found a filed UCC-1 that was not explained during the sale
- You need clarification about a recorded filing or termination after paying off the loan
- Something just doesn't feel right about your financing
If any of these sound familiar, start with our guide on signs you might be a victim of solar panel financing fraud. Our post on how to get out of a solar loan you didn't agree to covers your legal options. And our solar fraud page explains how we help homeowners in exactly these situations.
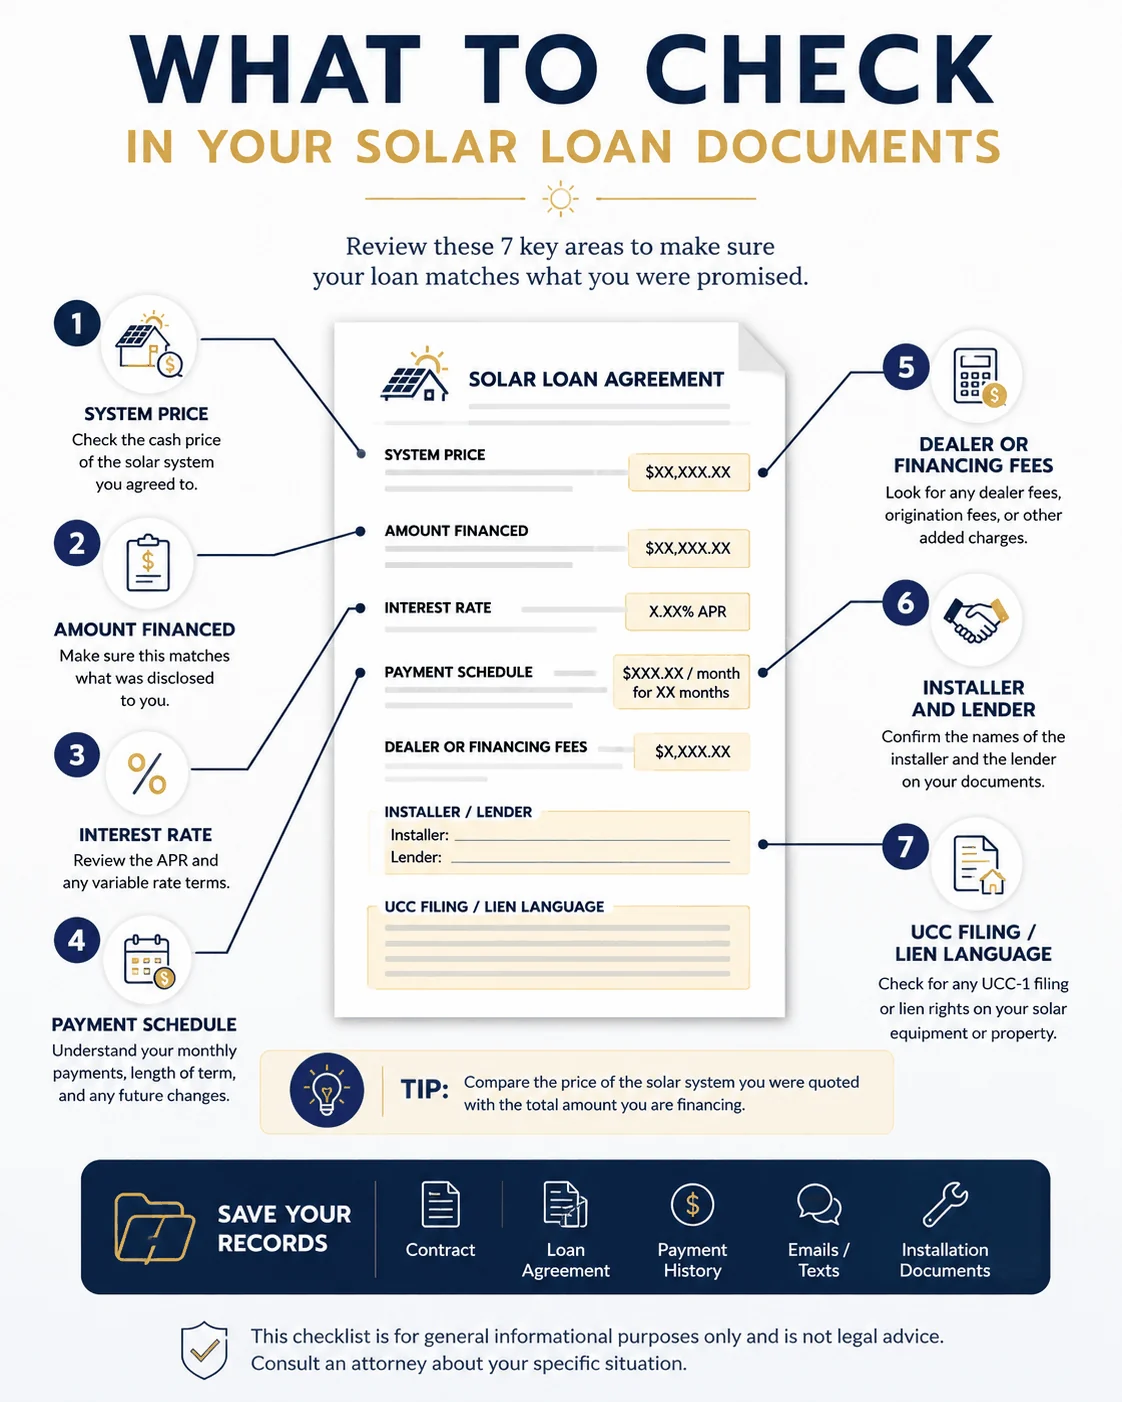
What You Should Do Right Now
Find your loan paperwork. Look for your original loan agreement and any documents that show the total amount you borrowed. Compare that number to the price you were quoted for the solar system. If there's a big gap, that's a red flag.
Ask for your payment history. You can request this from your loan servicer. Look at what your starting loan balance was. If it's a lot higher than the cost of the solar work, that difference could be a hidden dealer fee.
Write down what's wrong. If your system doesn't work right, your bills haven't gone down, or the installer won't call you back — write it all down. Dates, dollar amounts, names.
Talk to a lawyer. The Minnesota case is big news. But what matters for you is your specific loan, your state, and your situation. An attorney can review the documents and explain possible next steps.
Which Solar Financing Matters Does Bennett Legal Review?
Bennett Legal reviews GoodLeap, Sunlight Financial, EverBright and BrightOak solar financing involving any installer. EverBright matters are limited to loans and retail installment contracts, including EverOwn; EverBright leases and PPAs are excluded.
BrightOak PPAs require your contract and documented proof of a filed UCC-1. Search both county property records and state UCC records first, then provide the contract and recorded document or readable screenshots through secure intake. Staff search when you cannot find or access the filing. The extra recorded-filing proof condition applies specifically to BrightOak PPAs, rather than automatically to every BrightOak loan.
Solar Mosaic and Dividend Solar Finance are discussed here as defendants named in the historical public action. They are not offered as independently accepted financing matters. A different name on a current payment statement may reflect a servicing change; the original agreement and transfer notices need review.
For help identifying the company on your paperwork, use the installer directory. You can make an initial inquiry while gathering records. Sending an inquiry or documents is not a case-acceptance decision and does not create an attorney-client relationship.
Bennett Legal is not affiliated with GoodLeap, Sunlight Financial, EverBright, BrightOak, Solar Mosaic, Dividend Solar Finance or Fifth Third Bank. This is general information; the agreement, state and facts determine whether we can help.
Sources: Minnesota Attorney General's Office — Attorney General Ellison sues solar lenders over $35M in deceptive hidden fees; TIME magazine investigation into solar loan fraud; CFPB consumer complaint database; BBB records for GoodLeap LLC (formerly Loanpal / Paramount Equity Mortgage).
Official Minnesota Attorney General announcement checked on October 21, 2026. This source check is not an attorney review of your documents or a current docket search.
Free consultation
Solar panel contract problems?
We review GoodLeap, Sunlight Financial, EverBright loan/RIC and BrightOak financing matters. Free case evaluation.