That stack of papers the solar salesperson handed you — or the link they texted you right before the install crew showed up — is a 25-year financial obligation. It governs your rights, your obligations, and what happens to your home if anything goes wrong. Signing it without understanding it is like buying a house without reading the deed.
$170,000+ recovery
Against Sunlight Financial · Solar fraud arbitration
- $113,000 loan cancelled
- UCC lien removed
- Credit repaired
- $58,000 cash to client
Past results do not guarantee a similar outcome. Every case is different.
Here's what every section actually means — and where the danger zones are.
Free consultation
Solar panel contract problems?
We help homeowners fight back against solar fraud. Free consultation.
⚠️ This Guide Does Not Replace Legal Advice Solar loan agreements are among the most complex consumer contracts in existence — deliberately so. This guide will help you understand what you signed. But identifying violations, asserting your rights, and fighting a lender requires an attorney. No guide can do that for you. If something in your contract looks wrong, request an attorney-led solar contract review before you act.
Section 1: The Basics — The Parties and the Property
Read this graphic as text: Solar Loan Ecosystem Infographic
- The Borrower: You, the homeowner.
- The Lender: The financial institution providing the money (e.g., Sunlight Financial or GoodLeap). This relationship is how hidden fees get baked into your loan.
- The Installer/Dealer: Your installation company, acting as a middleman who "sells" your loan application to the lender.
- The Property: The agreement is tied to the solar energy system installed at your specific home address.
Section 2: The Money — The Truth in Lending Act (TILA) Disclosure Box
This is the most important financial section of your entire contract. Federal law requires this box to be clear and conspicuous — read it first, read it carefully, and compare every number to what you were told during the sales pitch.
- Annual Percentage Rate (APR): The true cost of your loan, including not just the interest rate but also any points, fees, and other charges. A salesperson might pitch a 1.99% "interest rate," but the APR might be 6.99%.
- Finance Charge: The total amount of interest you will pay over the entire life of the loan.
- Amount Financed: This is the number most homeowners miss. Compare it to the "cash price" of your system. If the Amount Financed is thousands of dollars higher than the cash price, the difference is likely a hidden dealer fee — an undisclosed charge added to inflate your loan principal. State attorneys general in Minnesota, Virginia, and New York have sued GoodLeap and Sunlight Financial over exactly this practice.
- Total of Payments: The total amount you will have paid back by the end of the 25-year term. Most homeowners have never seen this number — it is often three times the original system cost.
Read this graphic as text: TILA Box Infographic
⚠️ Spotting a discrepancy in the TILA box is step one. Knowing what to do about it — and whether it rises to a legal violation — requires an attorney who handles solar loan disputes.
Think your loan amount looks higher than what you were quoted? Start a free solar contract review.
Section 3: The Security — The UCC-1 Fixture Filing and Your Home
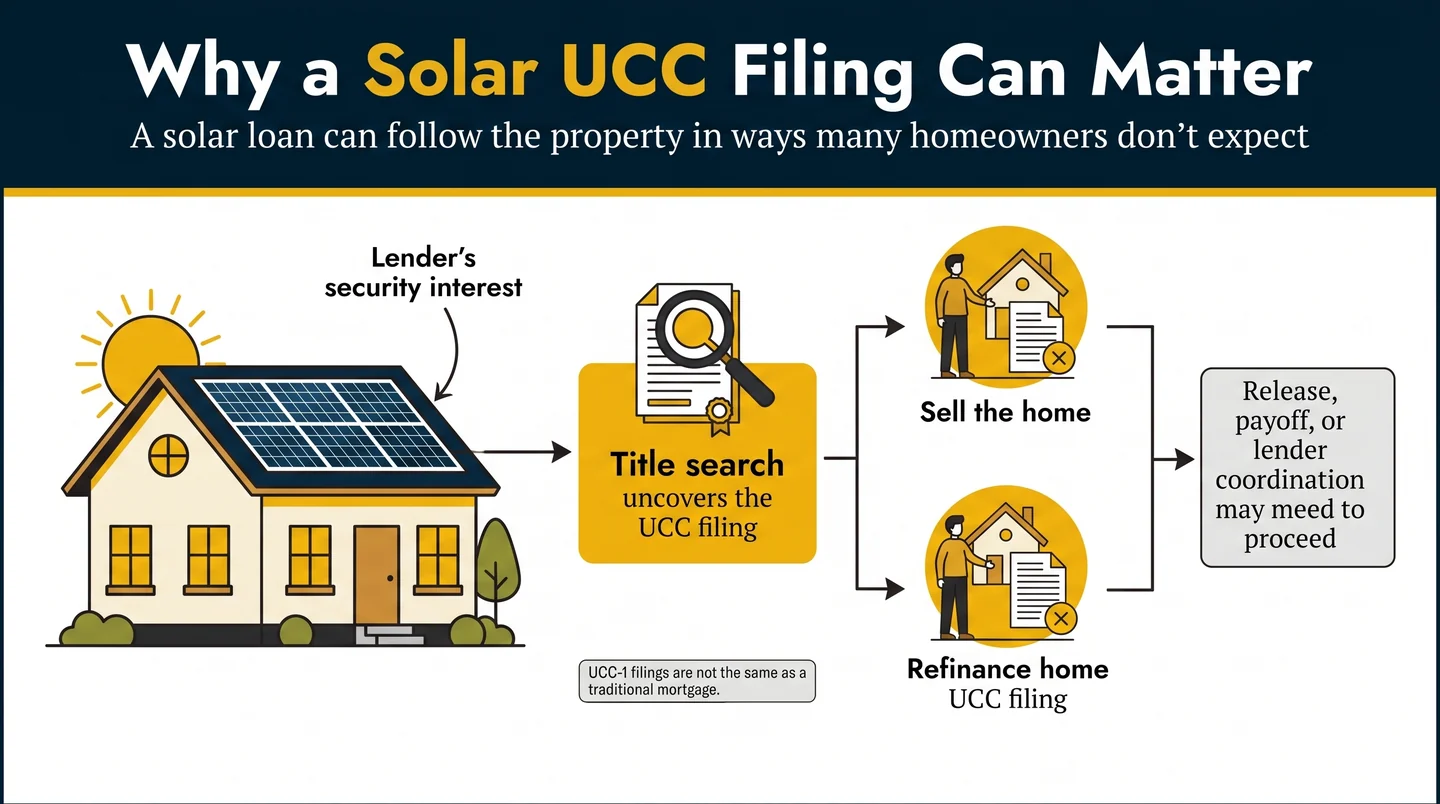
- What is a UCC-1 Fixture Filing? A lien the lender places on your solar panel system. Because the panels are permanently attached to your home, this UCC-1 lien effectively attaches to your entire property and will appear in any title search when you try to sell or refinance.
- How It Affects Your Home: Buyers and mortgage lenders will see this lien at closing. It can delay or kill a sale if it isn't properly released — even after you've paid off the loan. GoodLeap and Sunlight Financial have each received complaints about lien releases that never came.
- "Secured Party": The lender has a secured interest in your property. If you default, they have a legal right to be paid back. Understanding what "secured" means in practice is essential before you miss a payment or try to sell.
Section 4: The Promises — Your Covenants and Obligations
- Promise to Pay: You are committing to make all payments on time for the full loan term — no exceptions for a broken system, a disappeared installer, or a lender who ignores your calls.
- Promise to Maintain the Property: You must keep the system in good working order, at your own expense.
- Promise Not to Move or Alter: You cannot move the panels or make significant changes without the lender's written permission.
- Promise to Provide Access: You must give the lender or their agents access to inspect or service the equipment.
Section 5: The "What Ifs" — Default, Delinquency, and Acceleration
This section is where the lender's power becomes most visible. Read it carefully — it describes what they can do to you, not what they will do for you.
- Default: Usually triggered by a missed payment (often after 30–90 days) — but can also be triggered by letting your homeowner's insurance lapse or making unauthorized changes to the system.
- The Acceleration Clause: If you default, the lender can demand the entire remaining balance immediately — not just the missed payments. On a $40,000 loan three years in, that means a five-figure demand letter showing up in your mailbox.
- Collection Costs: If you default, you are responsible for all of the lender's legal fees associated with collecting the debt.
⚠️ The acceleration clause is one of the most dangerous provisions in any solar loan. If you receive a default notice or a demand for the full remaining balance, do not respond, negotiate, or send money without speaking to an attorney first. The window to protect yourself closes fast — and what you say in writing can be used against you.
Facing payment demands or a default notice? Talk to a solar fraud attorney →
Read this graphic as text: Missed Payments Animation
Section 6: The Exit Plan — Payoffs, Prepayment, and Subordination
- Loan Payoff: You must request an official "payoff quote" from the lender, valid for a specific number of days. Do not assume your current balance is your payoff amount — accrued interest and fees can make it significantly higher, and homeowners with GoodLeap loans have reported payoff amounts that don't match expectations.
- Prepayment Penalty: Most modern solar loans do not carry a prepayment penalty — but read this clause. If one exists, paying off your loan early could cost you thousands.
- Subordination Agreement: A document where the solar lender agrees to let a new mortgage lender take "first position" on your title. Without it, refinancing your home may be impossible. Some lenders are slow to provide these — or charge fees. If your lender is stalling, that may be legally actionable.
Section 7: The Fine Print — Clauses You Cannot Ignore
- Arbitration Clause: Many solar contracts require all disputes to go to private arbitration — meaning you give up your right to sue in court. This is not the dead end it sounds like. Bennett Legal has taken solar lenders including Sunlight Financial to JAMS arbitration and recovered $170,000 for a single client. The clause changes the arena — it does not eliminate your rights.
- Entire Agreement Clause: States that verbal promises from the salesperson are not legally binding. This is frequently used against homeowners who were lied to — but it can be challenged when the lie rises to the level of fraud or misrepresentation.
- Notice Clause: Specifies exactly how legal notices must be sent (e.g., certified mail to a specific address) to be legally valid. If you need to assert your rights under this contract, getting the notice wrong can void your claim.
⚠️ An arbitration clause and an "Entire Agreement" clause together create a high-friction environment designed to discourage you from fighting back. They are not insurmountable — but navigating them without an attorney who knows solar loan disputes is a serious risk.
Already signed a contract with these clauses? You may have more options than you think →
Read this graphic as text: Solar Contract Red Flags Checklist
The Bottom Line: Understanding Your Contract Is Step One. Fighting It Takes a Lawyer.
This guide gives you the vocabulary. It shows you where to look and what questions to ask. But the difference between spotting a problem and doing something about it is legal expertise — and in solar loan disputes, the margin for error is small and the lender's legal team is well-funded.
At Bennett Legal, we review solar contracts for TILA violations and hidden fees, audit existing loans for fraudulent misrepresentations, fight lenders who use bad-faith tactics to block a home sale or refinance, and challenge the "Entire Agreement" clause when a homeowner was tricked into signing based on lies. We also know how to get you out of a solar contract when the facts support it.
Get Your Free Contract Review →
Frequently Asked Questions
What is the most important section of a solar loan agreement?
The Truth in Lending Act (TILA) disclosure box. It contains the four numbers that matter most: APR, Amount Financed, Finance Charge, and Total of Payments. Compare the Amount Financed to the cash price you were quoted — any significant gap may be a hidden dealer fee.
What is a hidden dealer fee in a solar loan?
An undisclosed charge added to your loan principal — money that goes to the installer, not toward your solar system. If you were quoted $25,000 for a system but your loan is for $30,000, the $5,000 difference may be a dealer fee you were never told about. State attorneys general have sued GoodLeap, Sunlight Financial, and other major lenders over exactly this practice. For the latest on GoodLeap-specific complaints, payoff disputes, and lawsuit activity, see our GoodLeap Complaints and Lawsuit Updates (2025–2026).
What does an acceleration clause mean in a solar loan?
If you default — even by one missed payment — the lender can demand the full remaining balance immediately, not just the overdue amount. This can turn a $300/month problem into a five-figure demand letter overnight. If you receive one, contact an attorney before you respond.
Is a verbal promise from a solar salesperson legally binding?
Generally, the "Entire Agreement Clause" makes verbal promises unenforceable. However, if the salesperson deliberately misrepresented the product — claiming it was a government program, that panels would eliminate your electric bill, or that the system was pre-approved — that may constitute fraud, which carries a different legal standard and opens different avenues for relief.
What does it mean for a solar loan to be "secured"?
A secured loan means the lender has a legal claim on a specific asset if you fail to pay. For a solar loan, the panels are the collateral, secured through a UCC-1 fixture filing lien on your property. This lien can prevent you from selling or refinancing your home — even after the system stops working.
What should I do if I think my solar contract was fraudulent?
Document everything — the original sales pitch, what you were promised verbally, and how the actual loan or system differs from those promises. Then contact a solar fraud attorney before you stop making payments, sign anything new, or communicate with the lender in writing. Timing and sequencing matter enormously in these cases. Start with a free case evaluation →
Free consultation
Solar panel contract problems?
We help homeowners fight back against solar fraud. Free consultation.